Before You Lower the Price: 7 Seller Concessions That Could Help Sell Your Metro Atlanta Home
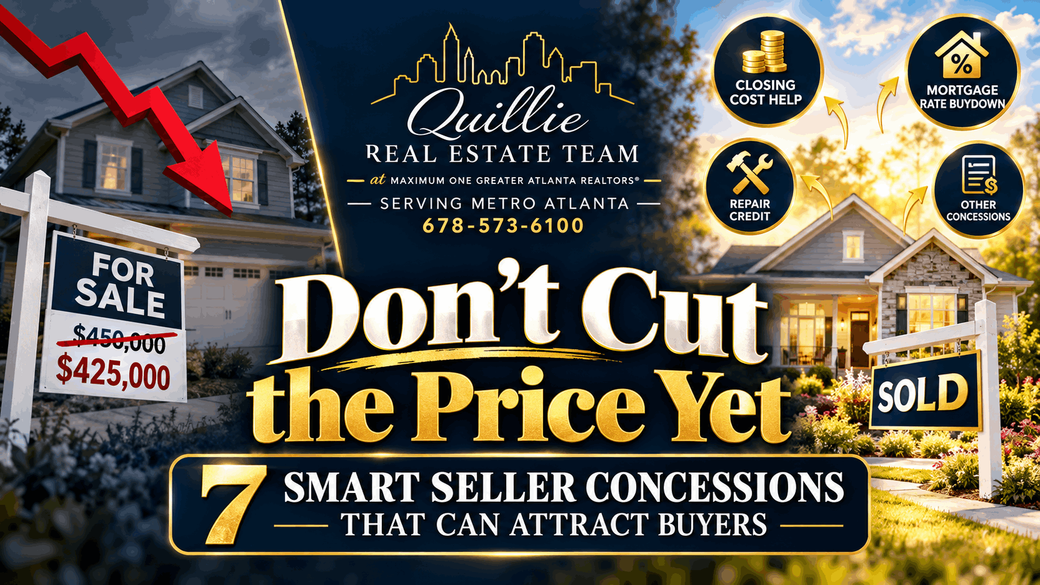
When a home is not getting the activity a seller expected, one of the first reactions is often:
“Do we need to lower the price?”
Sometimes the answer is yes.
But a price reduction is not always the only—or even the best—way to make a property more attractive to today's buyers.
Buyers are looking at much more than the asking price. They are also evaluating the monthly mortgage payment, cash required at closing, interest rate, repair expenses, HOA costs and the overall cost of moving into the home.
Where could the seller's negotiating dollars create the most value for the buyer while still producing an acceptable net for the seller?
What Is a Seller Concession?
A seller concession is an expense, credit or other negotiated benefit the seller agrees to provide as part of the transaction.
Depending on the buyer's financing, lender requirements and the terms of the purchase agreement, concessions may potentially help with expenses such as:
- Buyer closing costs
- Mortgage discount points
- Temporary mortgage-rate buydowns
- Permanent mortgage-rate buydowns
- Certain prepaid expenses
- Repair-related credits
- Home warranties
A concession should not automatically be viewed as money the seller is simply giving away. It should be evaluated as one part of the complete offer.
1 Help With the Buyer's Closing Costs
For some buyers, the biggest challenge is not the monthly mortgage payment. It is the amount of cash required to complete the purchase.
In addition to the down payment, buyers may have lender charges, title expenses, homeowners insurance, prepaid taxes and other closing-related costs.
A seller contribution toward allowable closing expenses can reduce the buyer's immediate cash requirement.
Why it may work: When two similar homes are competing for the same buyer, the property offering meaningful closing-cost assistance may be easier for that buyer to purchase.
2 Buy Down the Buyer's Mortgage Rate
Mortgage payments remain an important affordability consideration for many buyers. Instead of using every negotiating dollar for a price reduction, a seller may be able to contribute toward reducing the buyer's mortgage rate.
Depending on the buyer's loan program and lender, this may involve either a temporary or permanent rate buydown.
Temporary Rate Buydown
A structure such as a 2-1 temporary buydown can reduce the buyer's effective payment during the first years of the mortgage before the borrower reaches the full note-rate payment.
Permanent Rate Buydown
Discount points may also be used to permanently reduce the buyer's note rate for the full loan term.
The buyer's lender must determine the actual cost and interest-rate improvement.
Why it may work: Buyers frequently shop by monthly payment—not just purchase price. A financing concession can sometimes create more noticeable monthly savings than the same amount applied only to a modest price reduction.
Why Your Realtor’s Lender Relationships Matter
In today’s market, buyers are looking for every possible advantage to reduce their monthly payment. What many buyers may not realize is that a Realtor’s lender relationships can sometimes create access to additional financing strategies worth exploring.
Some lenders may offer special programs, promotional pricing, discounted rate options or other incentives through participating relationships. Availability, qualifications and terms vary by lender and loan program.
When you work with a Realtor who has established relationships with reputable local and national lenders, those connections may help identify opportunities such as:
- Lower-cost temporary buydowns such as 2-1 or 1-0 structures when available
- Reduced lender fees or lender credits that may help with eligible closing expenses
- Special rate-reduction programs or promotional financing opportunities
- Responsive underwriting and communication during the financing process
- Customized financing strategies based on the buyer’s goals, qualifications and available programs
These financing tools may help buyers address affordability without requiring the seller to carry the entire cost. In some transactions, lender incentives and negotiated seller concessions may also be used together when permitted by the applicable loan program.
Can a Realtor Actually Do This? Yes — Here’s How It Works.
3 Offer a Home Warranty
A buyer may love a home and still be concerned about unexpected expenses after closing.
A seller-paid home warranty can provide limited protection for specified systems and appliances under the warranty company's terms and conditions.
It does not replace a professional home inspection, and coverage varies by provider.
But it can provide additional peace of mind for buyers concerned about future repair expenses.
4 Address Repairs Strategically
Inspection negotiations can create friction when both parties become focused on individual repair items rather than the overall transaction.
But sellers do not always have to wait until they are under contract to discover what may become a problem.
Identifying important repair issues before buyers begin negotiating can give you more control over the condition of the property, the cost of the repairs and your estimated net proceeds.
Completing appropriate repairs in advance may also help protect the initial sales price you and the buyer agree upon because fewer unexpected inspection issues may surface after the contract is signed.
Instead of learning about a significant issue after accepting an offer—and then negotiating under contract deadlines—you may be able to address the problem on your own schedule, obtain your own repair estimates and make a more informed pricing decision before the home goes on the market.
Depending on the circumstances, a seller might:
- Complete appropriate repairs before listing the home
- Complete an agreed repair before closing
- Provide an allowable repair or closing-cost credit when appropriate
- Adjust another financial term of the agreement
- Negotiate a combination of solutions
Why it may work: Addressing known condition issues early can reduce surprises, strengthen buyer confidence and help the seller maintain better control over both the transaction and estimated net.
The appropriate solution still depends on the property, the buyer's financing and whether the lender or appraiser requires a particular repair to be completed.
5 Help With Certain HOA or Prepaid Expenses
Homes in homeowners associations and condominium communities can involve additional expenses around closing.
Depending on the transaction and financing rules, certain allowable prepaid or HOA-related expenses may sometimes be addressed through seller concessions.
To a buyer carefully managing cash-to-close, even a relatively small upfront expense can matter.
6 Include Appliances or Other Negotiable Property
Sometimes the buyer's concern is not purely mortgage-related.
A buyer moving into a home may immediately need a refrigerator, washer, dryer or other household items.
If a seller already intends to leave certain items, including them in the negotiation may increase convenience and reduce the buyer's immediate move-in expense.
Personal property should be documented carefully because lenders and appraisers may have specific requirements concerning how it is treated in a real estate transaction.
7 Offer Timing Flexibility
Not every valuable concession has a dollar sign attached to it.
A buyer may be coordinating:
- The end of a lease
- The sale of another home
- A job relocation
- School schedules
- Movers
- Temporary housing
A seller who has flexibility regarding the closing date or possession may make the entire transaction more attractive.
Price Reduction or Seller Concession?
This is where seller strategy becomes especially important.
Suppose a seller is prepared to give up several thousand dollars to make a home more competitive.
The question does not necessarily have to be:
“How much should we reduce the price?”
Another question may be:
“Where can those dollars create the most value for the buyer while still producing an acceptable net for the seller?”
For one buyer, closing-cost assistance may be most valuable.
For another buyer, the monthly payment may be the problem.
Another buyer may be comfortable with the price but concerned about repairs.
That is why negotiating the entire transaction can sometimes be more effective than negotiating only the sales price.
The Seller's Net Still Matters
A higher sales price does not automatically mean a better offer. Seller concessions, repair obligations and other negotiated expenses can materially change what the seller actually receives at closing.
There is an important difference between being flexible and giving away equity unnecessarily.
Every concession should be evaluated against the seller's estimated proceeds—not simply the headline purchase price.
For example, an offer at a higher price with substantial closing-cost assistance and repair obligations may produce a lower net than another offer with a slightly lower price and fewer concessions.
That is why I prefer to compare the entire offer before recommending which proposal is strongest for the seller.
Know What Your Home May Be Worth Before Deciding What to Concede
Before deciding whether to reduce your price, contribute toward closing costs or help a buyer lower their mortgage rate, start with a clearer picture of your home's current value.
There Are Limits on Seller Concessions
Seller concessions are not unlimited.
Maximum allowable contributions may vary depending on factors such as:
- Loan program
- Occupancy
- Down payment
- Loan-to-value ratio
- The type of expense being paid
- Lender or investor requirements
Conventional, FHA, VA and USDA financing do not necessarily follow identical concession rules.
For that reason, the buyer's lender should confirm what is permitted before a concession is finalized.
What This Means for Metro Atlanta Sellers
A successful selling strategy is increasingly about more than putting a property on the market and waiting for an offer.
Buyers may be comparing several homes and asking:
“Which home gives me the best overall financial opportunity?”
A seller may compete through:
- Price
- Condition
- Presentation
- Closing-cost assistance
- Mortgage-rate assistance
- Repair strategy
- Timing
- Overall contract terms
The right combination depends on the property, price range and local competition.
A strategy that works for a home in Douglasville may not be the best strategy for a property in Marietta, Smyrna, Mableton, Dallas, Hiram, Powder Springs or another Metro Atlanta community.
Before You Reduce Your Price, Run the Numbers
Price reductions still have an important place in real estate.
If a property is materially overpriced compared with competing listings and recent comparable sales, concessions alone may not solve the problem.
But when a home's price is reasonably aligned with the market, a targeted concession may sometimes address the buyer's actual concern more effectively.
That is why I prefer to look at the entire transaction before recommending that a seller simply reduce the price.
The goal is not just to get an offer. The goal is to structure a transaction that makes sense for the buyer while protecting the seller's position as much as the market allows.
Thinking About Selling a Metro Atlanta Home?
Before reducing your price or agreeing to a buyer's concession request, let's look at the numbers.
We can compare your home's position in the market, competing properties, possible buyer incentives and—most importantly—what each option could mean to your estimated proceeds.
Talk About Selling My Home Check Your Home ValueServing Real Estate Clients Since 1998
Categories
Recent Posts
GET MORE INFORMATION